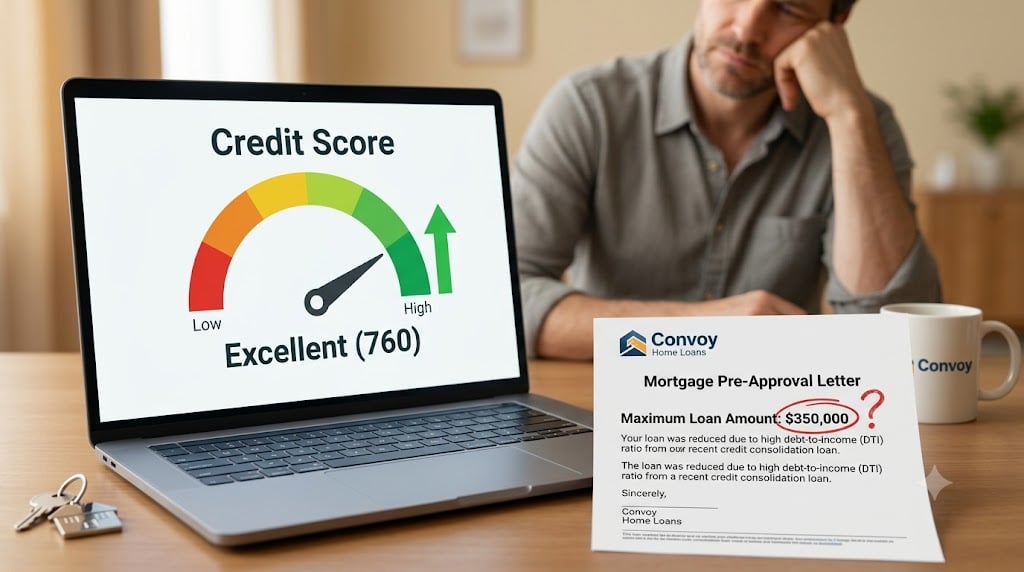
The Credit Moves That Backfire Right Before a Mortgage
Meta description: Closing a paid-off card, consolidating debt, or disputing an old account can lower your buying power. Here's what mortgage underwriting actually rewards.
Someone decides to get serious about buying a house. They pay off an old credit card and close it, because that feels like the responsible thing to do.
Their score drops eleven points.
This happens constantly, and it's the clearest example of a broader problem: most credit advice is written for consumers generally, and mortgage lending doesn't work the way consumer credit apps assume it does.
The score you're watching probably isn't the one being used
Mortgage lenders pull older FICO models, usually FICO 2, 4 and 5 depending on the bureau. Credit Karma and most free apps show you VantageScore. These are different scoring systems that weigh things differently, and the number you've been tracking may be off from your mortgage score by a meaningful margin in either direction.
Two more rules that surprise people:
Lenders use your middle score, not your highest and not an average. Three bureaus, three scores, they take the middle one.
On a joint application, they generally use the lower of the two middle scores. So if you're at 780 and your spouse is at 690, the file is a 690 file. This matters enormously for where you focus your effort, and plenty of couples spend months improving the wrong person's credit.
Five moves that tend to backfire
Closing a paid-off card. You just removed that card's limit from your available credit, which raises your overall utilization. The account also stops aging. Pay it off, then leave it open and put a recurring small charge on it.
Opening new accounts to build history. A new account adds an inquiry and drops your average account age. In the six months before a mortgage application, this reliably costs you points rather than earning them.
Consolidating card balances into a personal loan. Your score may improve, and your DTI can get worse, because the loan's fixed monthly payment might exceed the minimums you were paying across those cards. Since your loan amount is usually capped by DTI rather than by score, this can shrink your approval even as the number goes up.
Filing disputes. This is the expensive one nobody warns about. An account flagged as being in dispute on your report can stall underwriting, because underwriters often can't proceed until the dispute is resolved. People run a batch of disputes through a consumer app to clean up their file, then find their loan frozen weeks later. If something on your report is genuinely wrong, dispute it well before you apply, not during.
Paying off old collections without asking first. Sounds obviously good, often isn't. Depending on the scoring model, paying an old collection can update the activity date and cost you points. And the underwriting rules are more nuanced than most people assume: on many conventional loans, non-mortgage collections don't have to be paid off at all for a primary residence, and medical collections are frequently treated differently from other debt. Find out what your specific loan actually requires before you write the check.
What does work
Targeted paydown on revolving balances. Utilization is the fastest-moving lever you have. Getting your reported balances down, ideally into the low single digits as a percentage of your limits, produces real movement. Both overall utilization and per-card utilization count, so a single maxed card can hurt you even if your total is low.
Rapid rescore. If you're close to a pricing threshold, your loan officer can pay down specific balances, obtain updated documentation from the creditors, and have the bureaus reflect it in days instead of waiting a full billing cycle. Two things to know: only a lender can initiate this, so it's not something you can do on your own, and it only reflects accurate updated information. It doesn't remove legitimate negative history.
Knowing where the thresholds are. Pricing improves in tiers, generally in twenty-point bands. Sitting at 738 versus 740 can cost real money over the life of the loan for the sake of two points. This is exactly the situation rapid rescore exists for, and it's worth asking your loan officer to run a simulation before you assume you're stuck.
If you have a thin file
Twelve months of documented rent, utilities and insurance payments can serve as alternative credit on several programs. That's usually a better path than opening three cards two months before applying.
Being added as an authorized user on a longstanding account belonging to a family member can also help legitimately. What you should avoid is paying a service to add you to a stranger's account. That's tradeline renting, it's fraud, and underwriters look for it.
One thing not to worry about
Shopping multiple lenders. Mortgage inquiries made within a short window are generally treated as a single inquiry by scoring models, precisely so that rate shopping isn't penalized. Fear of inquiries keeps people from comparing offers, and it costs them far more than the inquiries would have.
The practical advice
Before you close an account, consolidate anything, dispute anything, or pay off a collection, ask a lender to look at your actual mortgage credit report first. Most of these decisions are cheap to get right and expensive to reverse, and the reversal usually happens at the worst possible time.
We'll pull your report, tell you what's actually holding you back, and run the numbers on whether a targeted paydown gets you to a better pricing tier.
Call 800-913-2169.