How Houses Actually Get Appraised (And Why It Matters)
Meta description: An appraisal is more than just a home inspection. Here is how appraisers evaluate your home's worth, how comps work, and what happens if the value comes in lower than expected.
You found the house. Your offer was accepted. You are officially under contract and the finish line is in sight. Then your loan officer mentions they ordered the appraisal.
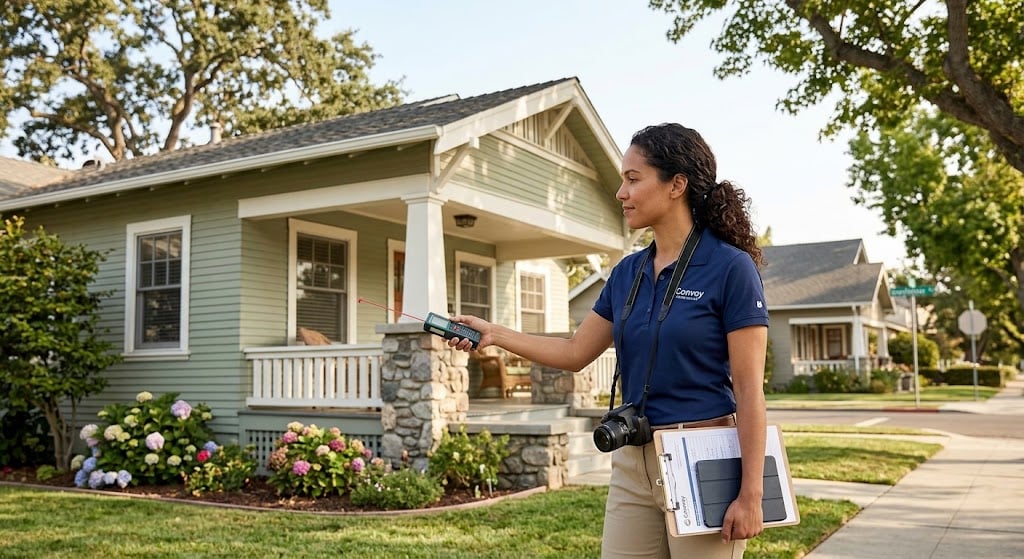
For a few days, everything pauses. A stranger walks through the property, takes some photos, measures the walls, and suddenly hands down a final number that dictates whether your mortgage moves forward.
It feels subjective. It feels like a black box.
But an appraisal is not a random guess. It is a highly structured math problem designed to answer one specific question for the lender: if you stop paying your mortgage tomorrow, can the bank sell this house and get their money back?
Where the confusion starts
Most people think the appraiser is there to make sure the house is in good shape. That is an inspector's job.
An inspector works for you. They crawl under the house and look for termites, leaky pipes, and bad wiring. They want to make sure you are not buying a money pit.
An appraiser works on behalf of the lender. They do not care if the dishwasher is loud or the paint is an ugly color. They care about value, condition, and marketability. They look for major safety hazards, sure, but their primary job is to prove the house is worth the money you are borrowing to buy it.
How they find the number
Appraisers do not invent a price. They compare the home to recent sales in the exact same neighborhood. These are called comparable sales, or comps.
They look for homes sold in the last three to six months. They want similar square footage, the same number of bedrooms and bathrooms, and similar lot sizes.
If your house has a pool and the comp does not, the appraiser adds value to your home's side of the ledger. If the comp has a brand new kitchen and yours has formica counters from 1994, they subtract value.
It is a balancing act. They make adjustments until they find a baseline number that reflects what buyers are actually paying for similar homes right now.
Automated valuations and waivers
Sometimes a human never even visits the house.
Fannie Mae and Freddie Mac have massive databases of property records. If you are putting down a large down payment and buying in a neighborhood with plenty of recent data, the system might issue an appraisal waiver. The algorithm agrees with the purchase price automatically.
When this happens, you save a few hundred dollars and shave days off your closing timeline. Just know that waivers are granted by the automated mortgage system based on the math. They are not something your loan officer can manually choose to apply.
What happens when the appraisal comes in low
This is the part everyone dreads. You agreed to pay $500,000, but the appraiser says the house is only worth $480,000.
Your lender will only base your loan on the appraised value. If there is a $20,000 gap, the money has to come from somewhere. You have a few options.
You can ask the seller to lower the price to the appraised value. In a buyer's market, they usually will.
You can pay the difference in cash. The lender still gives you a mortgage based on the $480,000, and you bring an extra $20,000 to the closing table.
You can meet in the middle. The seller drops the price by $10,000, and you bring $10,000 in cash.
Or you can walk away. Most contracts have an appraisal contingency that lets you cancel the deal and keep your earnest money if the numbers do not work out.
Can you fight a bad appraisal?
Yes, but it is an uphill battle. You cannot just complain that the value is too low. You have to prove the appraiser made a factual mistake.
If they listed the square footage incorrectly, missed a bedroom, or used comps from a completely different school district, your loan officer can file a Reconsideration of Value. You provide better comps, and the appraiser reviews them. Sometimes they change the number. Often they do not.
What to do this week
If you are buying, make sure your real estate agent includes an appraisal contingency in your contract. Do not waive it unless you have a pile of extra cash and completely understand the risk.
If you are refinancing, tidy up the house before the appraiser arrives. A messy house does not technically lower the value, but appraisers are human. Make it easy for them to see the home's potential.
Write down a list of any major updates you have done. A new roof, a new HVAC system, or a kitchen remodel all matter. Hand the list to the appraiser when they walk in so they do not miss your hard work.
Before you sign
Appraisals are just a snapshot in time. They protect you from overpaying, and they protect the lender from lending more than the property is worth.
Do not let the process intimidate you. The numbers usually work out, and when they do not, it is often a sign that you need to rethink the deal anyway.
If you want to know what to expect in your specific neighborhood, or if you are wondering if your loan might qualify for a waiver, let us know.
That is a conversation we have every day at Convoy Home Loans. Reach out and we will walk through the exact steps for your property.