Your Write-Offs Are Why You Can't Get Approved
Meta description: Self-employed borrowers get denied on income all the time while running profitable businesses. Here's what underwriters actually count, and what to do about it.
A contractor came to us last year doing about $600,000 gross. Good business, ten years in, no debt to speak of. His bank had turned him down on a $700,000 purchase and told him his income was insufficient.
His tax returns showed $71,000.
Nothing was wrong. His CPA had done exactly what a good CPA does, which is take every deduction he was entitled to. But that's the number the underwriter has to work with, and this is the tension self-employed borrowers run into constantly: the tax strategy that saves you money in April is the same one that shrinks you on a mortgage application.
What underwriters actually count
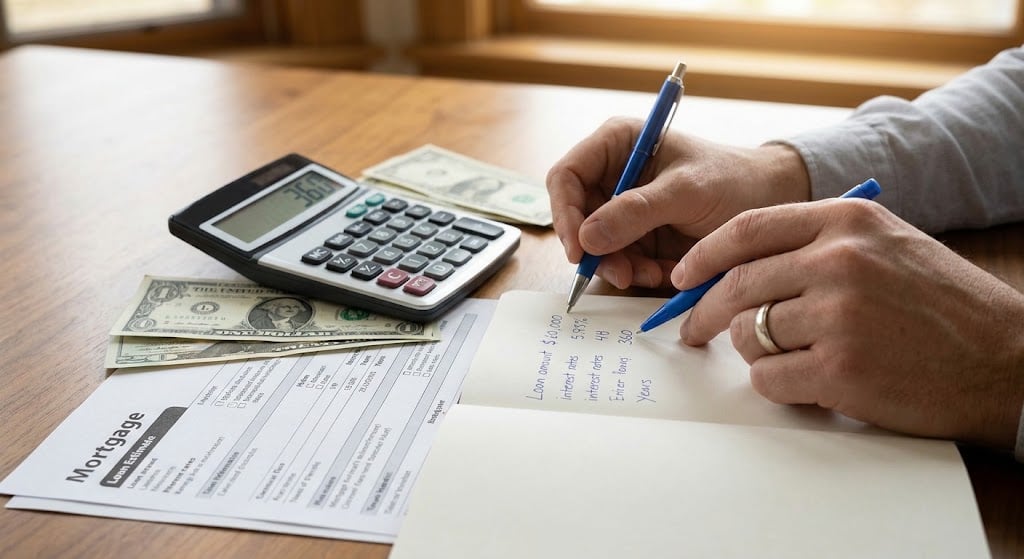
Not your gross revenue. Not your deposits. For a sole proprietor it's your net from Schedule C, and for an S-corp or partnership it's a combination of your K-1 and the business returns. They average it over two years, and if the second year came in lower than the first, they'll usually use the lower figure rather than the average.
So a strong year doesn't rescue a weak one, and a business that's growing gets underwritten as though it isn't.
The part most people don't know
Some deductions get added back.
Depreciation is the big one. It's a paper expense, no cash left your account, and underwriters add it back to your qualifying income. Same with amortization and depletion. The business-use-of-home deduction gets added back. So does the depreciation component of vehicle mileage, which for anyone driving 25,000 business miles a year is not a small number. One-time expenses that clearly won't recur can sometimes be added back with documentation.
It cuts the other way too. The non-deductible portion of meals and entertainment gets subtracted, and so does anything the underwriter reads as an obligation you'll keep paying.
The practical point is that your qualifying income is almost never the number on the bottom of your return. It's frequently higher, sometimes by a lot. We've had people talk themselves out of buying based on a number that was wrong by $40,000 a year. Before you assume you don't qualify, have someone actually run the calculation.
Timing is the whole game
Because it's a two-year lookback, the returns you file this spring are the ones underwriting a purchase two years out. That's the thing to internalize.
If you know you want to buy in 2028, the conversation with your CPA needs to happen now, not the week you find a house. By the time you're in contract, your returns are filed and there's nothing to be done about them.
To be blunt about the trade-off, though: reporting more income means paying more tax. For a self-employed borrower in California, adding $20,000 of reported income might cost somewhere in the neighborhood of $7,000 to $8,000 once you count self-employment tax and state, and that's real money spent to buy qualifying capacity. Sometimes that math works and sometimes it doesn't. It depends on the size of the purchase, how long you'll hold it, and whether a different loan product gets you there without the tax bill.
That's a conversation for you, your CPA, and your loan officer in the same room, and it should happen before the returns are filed. We're not tax advisors and we won't tell you how to file. We can tell you what a given set of numbers will qualify for, which is the piece your CPA doesn't have.
When tax returns aren't the right tool
Sometimes the answer isn't adjusting the returns at all. There are products built for exactly this situation:
Bank statement loans. We qualify you on 12 or 24 months of deposits instead of tax returns, applying an expense factor to arrive at income. For a business with heavy legitimate write-offs and healthy cash flow, this often produces a qualifying income two or three times what the returns show.
Profit and loss loans. For some borrowers, a CPA-prepared P&L covering the recent period does the work, with bank statements supporting it.
Asset-based qualifying. If you're liquid but your income is lumpy, we can calculate qualifying income from your asset position instead.
DSCR loans. For rental purchases, we qualify the property on its own rent rather than looking at your personal income at all. No tax returns enter the file. Worth being clear that this is an investment-property product, so it won't work for the house you're going to live in, including a house hack where you're occupying a unit. Different products for those.
These carry higher rates than conventional financing and often a prepayment penalty, so they aren't automatically the answer. But for someone who'd otherwise be told no, or told yes at half the loan amount they need, the comparison isn't against a conventional rate. It's against not buying.
If you're self-employed and you've been told no, or you're planning a purchase a year or two out and want to know what your returns will support before you file, call us at 800-913-2169. If the timing question is the one you're sitting on, earlier is genuinely better. The returns you file next month are the ones we'll be reading.