How to Plan the Right Mortgage Strategy in Today's Market
Meta description: Securing the right mortgage can be complex. Here is how to navigate today's market, understand the latest rate updates, and prioritize financing that fits your strategy.
You found the property. You reviewed the inspection report. You are officially ready to lock in your mortgage and build your equity. Then you look at today's rate updates.
For a moment, everything feels overwhelming. The 30 year fixed mortgage rate is hovering around 7.24 percent today [cite: 1.2.4], borrowing costs for 30 year refinances just jumped to 7.74 percent [cite: 1.2.1], and making the monthly budget actually cash flow feels harder than ever.
It feels stressful. It feels like a second full time job.
But funding a property is not a guessing game. It is a highly structured process of underwriting and analysis designed to answer one specific question for your portfolio: if we borrow this capital today, will the return on investment actually work for us?
Where the confusion starts
Most new buyers think the first step is picking a loan product. That is actually the last step.
A casual online scroll works for daydreaming. You look at 15 year mortgages, 5/1 ARMs, and luxury jumbo loans. You want to make sure the monthly payment looks beautiful.
A serious financing strategy relies on hard data. You do not care about the trendy rate buy downs yet. You care about the 10 year Treasury yield sitting over 5.1 percent [cite: 1.2.3], economic shifts, and non negotiable financial necessities. You look for payment potential, sure, but your primary job is to prove the math works before you ever sign the closing papers.
How you find the number
Buyers do not invent a target interest rate out of thin air. They compare their capital to current market realities. These are the numbers that dictate your yield.
Right now, buyers are closely watching the Federal Reserve, and elevated interest rates are compressing margins [cite: 1.2.3].
If you are buying with a partner and one of you wants to max out the purchasing power while the other wants to keep cash reserves high, you have to balance the ledger. If one wants a 30 year fixed and the other wants a 15 year fixed, you have to find common ground.
It is a balancing act. You make adjustments until you find a target monthly payment that you are actually comfortable accepting right now.
Wants, needs, and compromises
Sometimes a buyer only needs a simple rate adjustment.
The current market rewards very specific financial choices. If you are looking to maximize your budget, September 29 data shows that a 5/1 ARM has dropped 19 basis points to 6.71 percent [cite: 1.2.4]. A 15 year fixed rate has dipped to 6.63 percent [cite: 1.2.4]. The reality of what actually saves you money dictates your choices.
When this happens, you have to rely on your strict investment criteria. Just know that the perfect 3 percent rate rarely exists anymore. It is not something you can magically manifest.
What happens when you disagree
This is the part every purchasing partnership dreads. You love the idea of paying discount points upfront for a massive rate drop, but your partner wants to keep the cash in the bank for a quicker safety net.
Your lender will base your loan on your finances and the appraisal value of the asset, but you still have to manage the strategy. If there is a gap in your visions, the compromise has to come from somewhere.
You have a few options.
You can prioritize the down payment. In a mortgage search, minimizing your principal balance usually wins out.
You can split the difference. You buy down the rate slightly, but keep a portion of your existing savings.
You can meet in the middle. You focus your budget entirely on a 15 year fixed rate to guarantee a faster payoff timeline.
Or you can keep looking. Most buyers have a moment where they pause the process to rethink their loan limits if the monthly estimates simply do not pencil out.
Can you time the market?
Yes, but it is an uphill battle. You cannot just wait for mortgage rates to drop drastically. You have to make decisions based on long term wealth building.
If rates go down next year, you can always refinance out of a 7 percent loan to improve your cash flow [cite: 1.2.2]. If bond markets stabilize, you might get better deals on borrowing costs. You watch the trends, and the market shifts. Sometimes rates flatten out. But waiting on the sidelines often costs more in missed home equity.
What to do this week
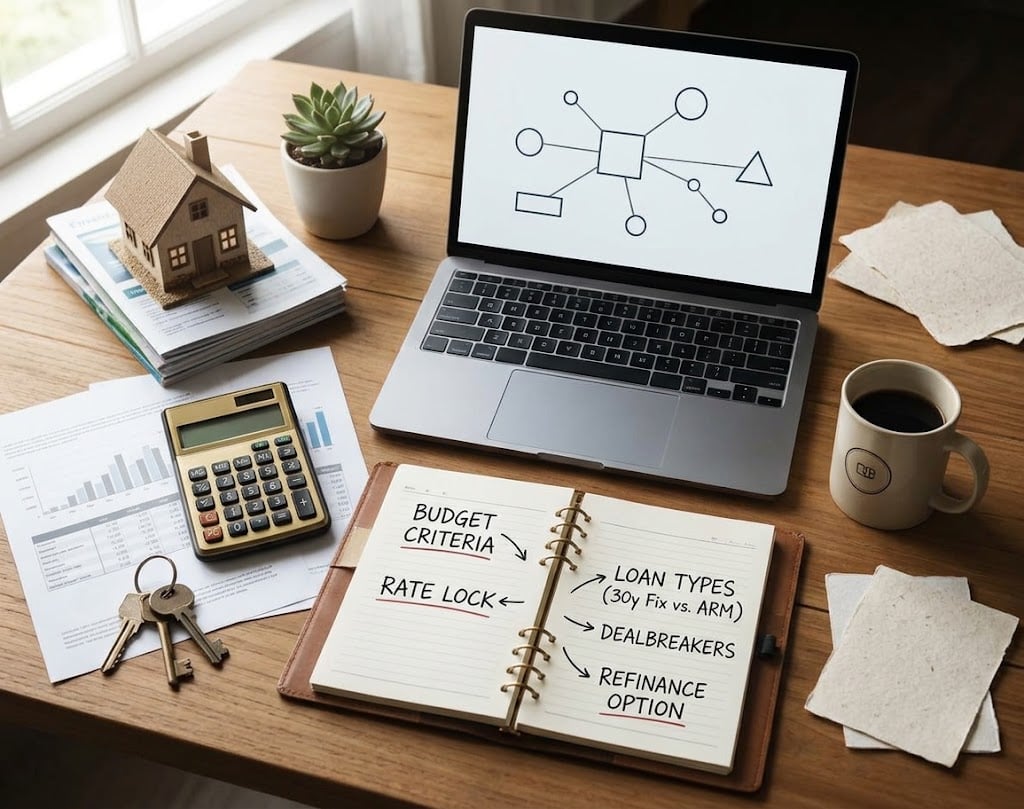
If you are starting your financing planning, make sure you write out a list of your strict budget criteria. Do not skip this step unless you completely understand the risk of getting emotional over expensive monthly payments later.
If you are already getting quotes, get pre approved for your home loan or get your proof of funds in order before you start making offers. A pre approval letter does not guarantee a perfect rate, but sellers are human. Make it easy for them to take your offer seriously.
Write down a list of any major dealbreakers. High HOA fees, severe foundation issues, or outdated electrical panels all matter to your lender. Hand the list to your real estate agent so they do not waste your hard work.
Before you sign
Securing a mortgage is just a snapshot in time. It protects your asset from depreciation, and it builds your financial future.
Do not let the process intimidate you. The numbers usually work out, and when they do not, it is often a sign that you need to rethink your budget anyway.
If you want to know what to expect for mortgage rates in your specific target market, or if you are wondering what today's updates mean for your ROI, let us know.
That is a conversation we have every day at Convoy Home Loans. Reach out and we will walk through the exact steps to fund your next property.